
Amber Bannister
Real Estate ● 24 Feb 2026
The latest overview of New Zealand property values confirms what many buyers and sellers are already sensing: the sharp correction phase is behind us, and the market has moved into a period of consolidation.
While values remain below their peak, recent movements suggest the pace of decline has slowed significantly.
Short-Term Movement: Little Change Over Three Months
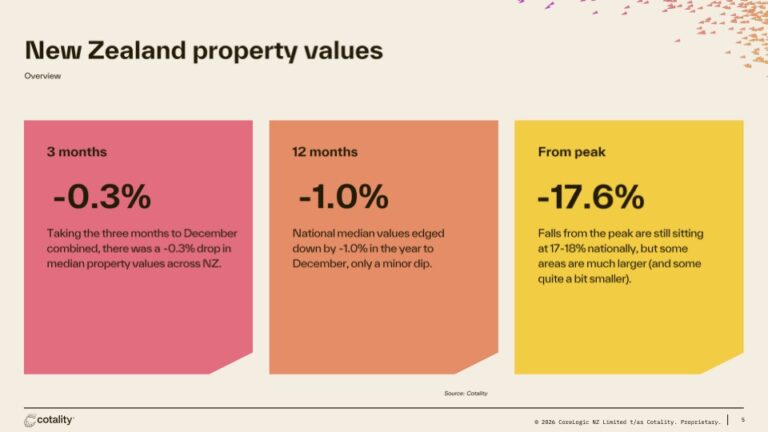
Over the three months to December, national median property values fell by just 0.3%.
This modest shift indicates a market that is no longer under heavy downward pressure. Instead, values are broadly holding steady as buyers and sellers find a new balance.
Annual View: Small Dip Over 12 Months
Looking at the past 12 months, national values edged down by 1.0%. In the context of the sharp declines seen in 2022 and 2023, this is a relatively minor adjustment.
It reinforces the view that 2025 was more about stabilisation than continued correction.
From Peak: The Big Picture
From the market peak, national property values remain around 17.6% lower. While this sounds significant, it reflects the unwinding of an unusually rapid price surge during the boom years.
Importantly, not all regions experienced the same rise — or the same fall. Some areas are still well below their peaks, while others have already recovered a meaningful portion of earlier declines.
What’s Driving the Current Stability
Together, these factors have helped bring greater balance to the market.
Why This Matters
For buyers, a stabilising market offers more certainty and less urgency. For sellers, it means pricing expectations need to be realistic, but conditions are no longer deteriorating.
For the market as a whole, this phase lays the groundwork for gradual recovery rather than another sharp cycle.
The big takeaway
New Zealand’s property market has largely found its footing. Values are only marginally lower over the past year, short-term movements are small, and the biggest adjustment from the peak is now behind us.
As 2026 unfolds, further gains are likely to be slow and uneven — shaped more by regional conditions than national momentum.
Source: Cotality – NZ Monthly Housing Chart Pack, February 2026