
Amber Bannister
Real Estate ● 27 Dec 2025
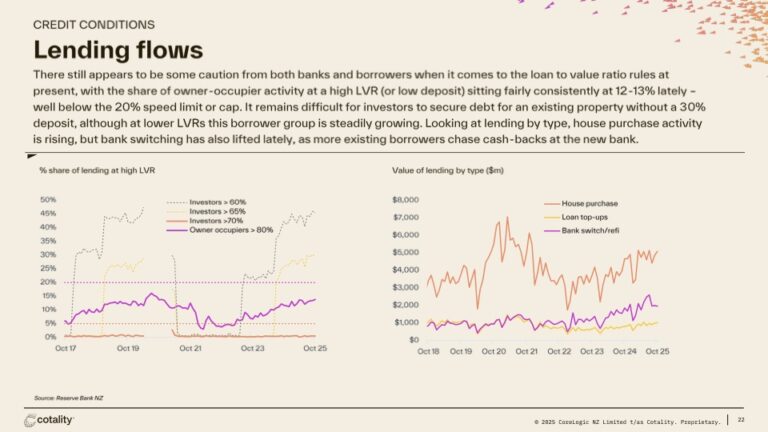
Lending activity in New Zealand is slowly picking up again — but it’s doing so cautiously. The latest credit data shows both banks and borrowers remain careful, particularly when it comes to low-deposit lending and investor borrowing.
Rather than a surge in new debt, the market is seeing a gradual normalisation in lending flows as confidence rebuilds.
High-LVR Lending Rem known but Controlled
Owner-occupiers using high loan-to-value ratios (LVRs) — meaning smaller deposits — continue to make up around 12–13% of lending. This level has remained fairly consistent in recent months and sits well below the Reserve Bank’s 20% speed limit.
This suggests banks are still supporting first-home buyers, but without taking on excessive risk.
Investors Still Face Tighter Lending Rules
For investors, credit conditions remain more restrictive. It continues to be difficult to borrow against existing properties without a 30% deposit, and high-LVR investor lending remains very limited.
That said, investor lending at lower LVRs is slowly increasing, pointing to a cautious return of investor activity — particularly among smaller or more experienced investors.
House Purchase Lending Is Rising
Looking at lending by type, lending for house purchases has been trending higher. This reflects:
While volumes remain below the highs of the boom years, the direction of travel is clearly upward.
Bank Switching and Refinancing Pick Up
One of the most noticeable trends is the rise in bank switching and refinancing. More existing borrowers are moving lenders, often to secure cash-back incentives or better interest rates.
This reflects increased competition between banks and greater borrower confidence to renegotiate lending terms.
Loan Top-Ups Remain Modest
Loan top-ups — often used for renovations or additional spending — remain relatively subdued. This suggests households are still prioritising financial caution over discretionary borrowing.
Spending is happening, but in a more controlled and deliberate way than during previous growth cycles.
The big takeaway
Lending flows show a market that is recovering carefully rather than rushing ahead. Banks remain disciplined, borrowers are more informed, and risk appetite is improving only gradually.
This combination points toward a more sustainable phase of growth — one built on affordability, confidence, and measured lending rather than excess.
Source: Cotality – NZ Monthly Housing Chart Pack, December 2025